
Corporate gifts in Ireland are not one compliance question. An employee voucher, a client hamper, a courtesy offered to a public official, and a parcel imported from outside the European Union follow different routes. The safest programme classifies the recipient and purpose before anyone chooses a product, then sends the case to the owner who can decide tax, payroll, ethics, privacy, and customs treatment.
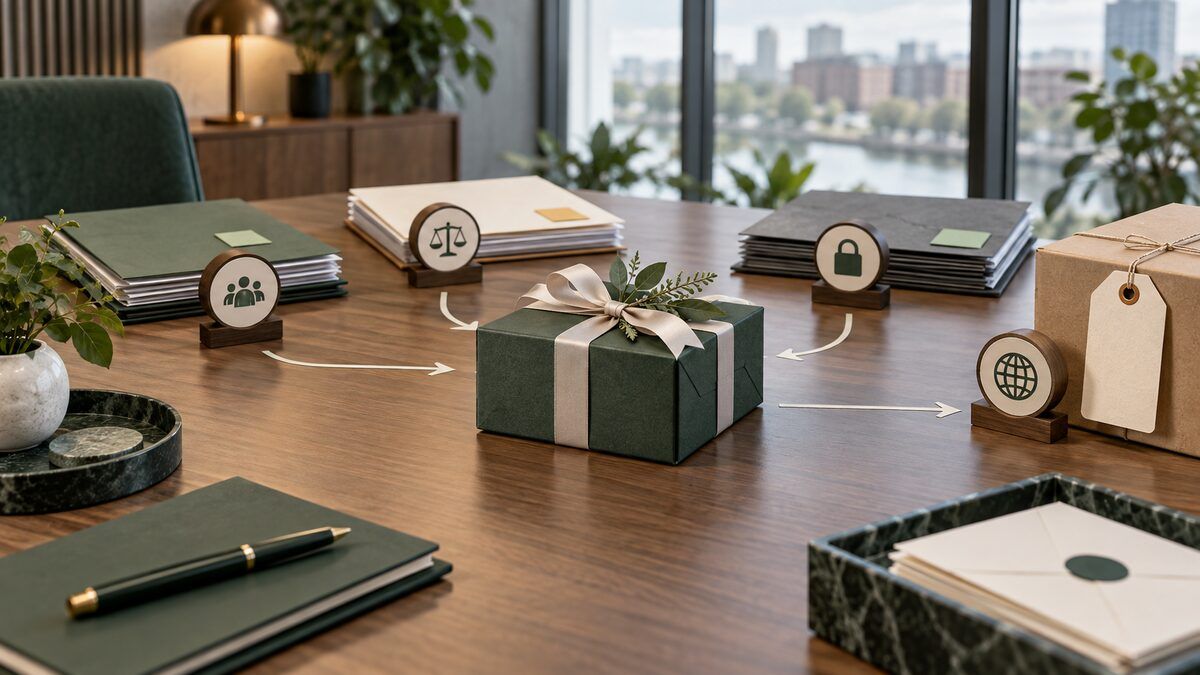
Caption: One corporate gift moves through distinct payroll, ethics, privacy, and customs decisions before fulfilment.
Start with the recipient, purpose, and legal owner
The first control is a routing decision, not a tax calculation. Ask whether the recipient is an employee, a worker whose status is uncertain, a client or prospect, a supplier, a public official, or a private individual receiving a personal gift. Record the business purpose, the entity paying, the market of dispatch, the destination, the planned value, whether cash redemption is possible, and whether the benefit is promised by contract. A single campaign may create several legal cases even when every recipient sees the same catalogue. Use the global corporate gift compliance hub for the broader control map and the gift and hospitality policy template to turn approved Ireland decisions into internal rules.
For employees, payroll owns the tax conclusion and reporting. Finance owns budget and evidence of value. Legal or ethics owns public-sector and influence risk. Privacy owns the lawful basis, notices, processor terms, retention, and cross-border data questions. Customs or a broker owns classification, origin, valuation, and import declarations. Programme operations may coordinate those decisions, but it should not replace them with a green cell or an assumed threshold.
Use the following matrix as a triage tool rather than legal advice. A case moves only when the named owner records a decision and the evidence required by that decision.
Table: Routing corporate gifts in Ireland by recipient and risk owner.
| Recipient or route | Primary review | Minimum evidence before send | Stop condition |
|---|---|---|---|
| Employee | Payroll and tax | Employment record, date, value, benefit count, cash-redemption test | Unknown annual total, contractual substitution, or unreportable event |
| Client or prospect | Finance, ethics, and account owner | Business purpose, recipient policy check, approval, invoice, VAT position | Active tender, hidden beneficiary, personal inducement, or missing approval |
| Public official | Legal or ethics | Identity and role, agency policy, written clearance, value, timing, purpose | No affirmative clearance or any appearance of influencing an official act |
| Imported parcel | Customs and logistics | Commodity description, value, origin, payer, importer, taxes, carrier record | False gift declaration, unknown importer, restricted goods, or uncertain value |
Apply the Small Benefit Exemption as a controlled payroll decision
The Irish Revenue Small Benefit Exemption guidance, last verified 20 September 2026, says that from 1 January 2025 an employer may give an employee up to five non-cash benefits in a year, with a combined value no greater than €1,500. A single benefit of up to €1,500 may qualify. If a single benefit exceeds €1,500, the full value of that benefit is taxable. If more than five benefits are provided, only the first five may qualify. Unused capacity does not carry forward.
The benefit must not be cash. Revenue also says a voucher or benefit that can be redeemed in full or in part for cash does not qualify. The face value of a voucher is generally its benefit value; nominal fees or postage may be disregarded only in the limited threshold context described by Revenue. The guidance requires the date and value to be reported under the enhanced reporting requirements, so fulfilment cannot be separated from payroll evidence.
Build an employee-benefit ledger keyed by the legal employer and employee identifier, not an email address or campaign row. Before reserving a gift, read the current-year count and cumulative value. Record the proposed item, face value or defensible market value, date it will be provided, cash-redemption result, funding entity, and whether it replaces pay or a contractual entitlement. Send those facts to payroll. Reserve capacity only after payroll returns an affirmative decision.
Do not design an automatic rule that labels every first five gifts below €1,500 exempt. The system cannot decide employment status, salary sacrifice, contractual entitlement, correct value, prior benefits from another team, or how a failure should be corrected. It can calculate and warn; payroll must conclude. If the legal employer changed during the year or records are incomplete after an acquisition, stop and reconcile rather than guessing.
Hypothetical case 1: employee recognition
Aoife has already received three qualifying non-cash benefits worth €900 in total from the same employer during 2026. Her manager proposes a €400 voucher that cannot be redeemed for cash. The workflow finds the prior ledger, calculates a proposed total of €1,300 and a fourth benefit, and sends the evidence to payroll. Payroll confirms that the item is discretionary, additional to salary, properly valued, and reportable. The programme records approval, provides the benefit, captures the actual provision date and value, and submits the required reporting evidence.
Now change one fact: another business unit issued two earlier benefits that were not loaded into the ledger. The proposed item would be the sixth. The workflow must stop, reconcile the missing events, and ask payroll how the proposed benefit should be treated. It must not split the voucher, rename the campaign, or use a different platform account to evade the count. Acceptance evidence is the reconciled ledger, payroll decision, reporting receipt, fulfilment receipt, and any correction record.
Keep client gifts separate from employee tax relief
The Small Benefit Exemption is an employment rule; it is not a general safe harbour for client, supplier, or prospect gifts. For a business recipient, document a legitimate business purpose, the organisation represented, the relationship owner, value, timing, source of funds, and the recipient organisation’s own gift policy. Ask whether a tender, procurement decision, inspection, claim, licence, grant, or contract renewal is active. A modest item can still be inappropriate when timing or secrecy creates influence risk.
Finance should determine the accounting and Irish Revenue VAT position using the specific goods, transaction, and recovery history. Do not publish a universal VAT answer from the gift’s retail price. The organisation may need to consider whether input VAT was deducted, whether a deemed supply or adjustment arises, whether the item is advertising material or a business sample, and what invoice evidence exists. Those questions vary with the facts and current law. The programme should capture the facts and store finance’s conclusion rather than invent a VAT result.
Use tiered approvals based on risk, not only price. A low-value item to a private-sector client after a completed event may need a manager and policy check. Any item connected with a public body, healthcare decision, procurement process, or regulated approval should route to legal or ethics regardless of value. Where the recipient’s policy prohibits gifts, use a neutral alternative such as a charitable option only if that alternative also passes the organisation’s policy and legal review.
Hypothetical case 2: client event
A software company wants to send the same locally sourced hamper to 40 private-sector event speakers in Ireland. The event owner supplies the speaker list, purpose, unit value, invoice, and timing. Ethics confirms there is no live procurement decision and requires each speaker to confirm their employer permits acceptance. Finance records the VAT conclusion for the actual goods and invoice. Privacy approves a recipient-controlled address collection flow. Operations sends only after both confirmations are present and retains the evidence packet.
One speaker works for a government agency and has not supplied written permission. The system separates that record, does not infer permission from the other 39, and routes it to legal. If clearance never arrives, the item is cancelled. The successful private-sector sends do not make the public-sector case safe. Acceptance evidence includes the invitation basis, recipient-policy confirmations, approvals, finance decision, address collection notice, dispatch records, and the cancelled exception.
Treat public officials and influence risk as a separate gate
Ireland’s Criminal Justice (Corruption Offences) Act 2018 is the official statutory starting point, but a gifting workflow should not try to reduce corruption law to a price limit. The legal question turns on purpose, advantage, relationship, timing, transparency, and the relevant organisation’s rules. The official full Act was verified on 20 September 2026; it does not create a universal safe gift amount, so this article does not infer one or replace legal advice.
Create a high-risk route for elected representatives, civil servants, regulators, state-agency staff, public procurement participants, and anyone acting for a public body. The requester must identify the person’s role and agency, the business interaction, any pending official action, the proposed item and value, who pays, who attends, and whether the offer will be recorded by the recipient organisation. Legal or ethics must give affirmative written approval. Silence, calendar acceptance, or a recipient saying “it should be fine” is not clearance.
The safe default is no send while the review is incomplete. Do not divide one gift into smaller transactions, route it through an event agency, describe hospitality as education, or deliver to a family member. Keep declined offers and cancelled requests in the audit record because they demonstrate that the control worked. If an organisation publishes a stricter policy, apply it even when another rule might appear more permissive.
Extend the same gate to private-sector influence risks. A buyer, auditor, medical professional, intermediary, or supplier evaluator may be subject to professional, contractual, or internal rules. The workflow should ask about active decisions and conflicts rather than assuming corruption risk exists only in government.
Build privacy into address and preference collection
The Data Protection Commission guidance for organisations and the GDPR require a defined purpose, lawful basis, transparency, data minimisation, security, retention limits, and accountability. A home address is not merely a shipping field. It is personal data that may expose where a person lives, and dietary or accessibility preferences may reveal more than the programme needs. The employer or sender remains responsible for deciding the lawful processing design even when a fulfilment provider collects the information.
Prefer a recipient-controlled claim flow. Send an invitation to a verified business contact or approved channel, allow the recipient to provide a delivery address and preference directly to the fulfilment service, and return only status information needed by operations. The campaign sheet normally needs an internal recipient reference, eligibility state, invitation state, market, expiry date, and fulfilment status. It usually does not need the full address, phone number, gift choice, or carrier history.
Before launch, document the controller and processor roles, purpose, lawful basis, data fields, recipients, sub-processors, hosting locations, transfer mechanism where relevant, retention schedule, deletion process, access control, incident route, and rights-request handling. Make the notice visible before collection. Do not bundle marketing consent with data needed to deliver the selected gift. If optional personalisation uses additional data, provide a separate and genuine choice.
Set an event-based retention clock. Delivery information can be removed after delivery, dispute, return, and statutory evidence needs are resolved, while a smaller financial or approval record may have a different retention period. Deletion should reach processors and cached exports, and completion should be evidenced. “Keep everything for audit” is not a retention schedule.
Privacy exception checklist
-
If an assistant enters an executive’s address, confirm authority and give the recipient an appropriate notice.
-
If a dietary preference could reveal health or belief information, collect only what fulfilment truly needs and obtain privacy review.
-
If address validation or support occurs outside the European Economic Area, document the transfer route and safeguards.
-
If a recipient withdraws before dispatch, stop optional processing and determine which minimum records must still be retained.
-
If a spreadsheet export is unavoidable, time-limit access, encrypt it, name an owner, and delete the verified copies after use.
Do not label commercial parcels as personal gifts
Revenue’s customs guidance on gifts, published 28 May 2026 and verified 20 September 2026, describes relief for a gift sent from a private individual outside the European Union to a private individual within the EU. It must be occasional, for personal or family use, correctly declared, have no commercial or trade element, and meet the stated value conditions. Revenue states an intrinsic-value limit of €45 for that specific relief and explains that VAT treatment changes when the consignment exceeds it.
A company-funded corporate gift does not become a qualifying private gift because the recipient did not pay. Do not instruct a seller or carrier to mark commercial merchandise as “gift” to obtain personal relief. Route company shipments through the correct commercial import process. Identify the importer of record, commodity description and code, origin, transaction or customs value, shipping and insurance components, Incoterm, restricted-goods checks, VAT and duty payer, and broker instructions before dispatch.
Use destination-aware catalogues so an approver sees landed-cost and import risk before selection. Where practical, fulfil from inventory already in the EU or from a supplier that can provide valid commercial documentation. Local fulfilment can reduce border uncertainty, but it does not answer payroll, VAT, ethics, or privacy questions. A parcel may be physically local and still be an inappropriate gift.
Treat alcohol, tobacco, perfume, food, plants, batteries, cosmetics, and other controlled or sensitive goods as specialist routes. Revenue’s personal gift page explicitly excludes or limits some categories, but a corporate programme should use current commercial rules and carrier acceptance criteria rather than borrowing personal allowances. If classification or import responsibility is uncertain, hold the order and obtain broker or customs advice.
Design one evidence packet for every decision
A defensible programme links the business request, approval, tax decision, privacy notice, fulfilment event, and financial outcome without putting all underlying personal data in one table. Create a stable case identifier and store references to the systems that own each fact. The evidence packet should show what was known when the decision was made, who decided, which policy version applied, and what actually happened.
Table: Minimum evidence by control stage.
| Stage | Required record | Owner | Acceptance test |
|---|---|---|---|
| Request | Recipient class, purpose, entity, market, proposed value, requester | Programme operations | All routing fields present; duplicate check passed |
| Decision | Payroll, finance, ethics, privacy, or customs conclusion with policy version | Named control owner | Affirmative decision, timestamp, actor, and conditions recorded |
| Provision | Immutable event key, actual value, date provided, receipt, status history | Execution owner | One approved case creates no more than one fulfilment event |
| Reporting | Revenue or payroll submission reference, VAT/customs record, corrections | Payroll or finance | Submission reconciles to actual event and value |
| Closure | Delivery, cancellation, return, refund, deletion, unresolved exception | Operations and privacy | Financial and data states reconciled; owner signs closure |
Protect the evidence from silent edits. A corrected recipient, value, or market should create a new version and may require reapproval. Store hashes or immutable event references where appropriate. Separate retention of audit facts from retention of addresses and preferences. A long-lived case identifier does not justify keeping every personal field for the same period.
Build reports around exceptions: cases waiting for payroll, public-sector reviews without clearance, address collection beyond its deadline, parcels without importer evidence, deliveries without reporting confirmation, and refunds not matched to budget. Aggregate campaign totals are useful, but the oldest unresolved case is often the better risk signal.
Run a pre-send control sequence
Make the workflow fail closed. A requester should not be able to send first and collect approval later. Each transition has one owner, required evidence, a deadline, and a defined return path.
-
Classify the recipient and relationship; confirm the paying legal entity and destination.
-
Record a specific business purpose, event, value basis, and any active decision or procurement process.
-
For employees, reconcile the annual benefit ledger and obtain payroll’s written tax and reporting decision.
-
For clients, obtain the recipient-policy check, ethics approval, and finance’s VAT/accounting conclusion.
-
For public officials or higher-risk roles, obtain affirmative legal or ethics clearance before any offer.
-
Approve the privacy design, notice, data fields, processor terms, transfers, access, and retention.
-
For imports, confirm commercial declaration, importer, classification, origin, value, restrictions, and tax payer.
-
Reserve an idempotent event key only after all required approvals are present and still valid.
-
Collect address and preferences through the approved recipient-controlled flow.
-
Recheck value, recipient, market, policy version, and approval expiry immediately before dispatch.
-
Reconcile delivery, employee reporting, VAT/customs records, refunds, budget, and deletion tasks.
The event key should represent one authorised provision, not one button click. A timeout creates an unknown result. Query the fulfilment state before retrying; do not create a second order simply because the first response was lost. A changed value, recipient, market, or item may invalidate the approval and should create a reviewed new version rather than reuse the old key.
Give operations a kill switch that stops new dispatches without deleting evidence. Define who may pause a campaign, what happens to accepted invitations, how expiring items are handled, and who authorises restart. Test the switch before launch. A control that exists only in a runbook but cannot stop the actual queue is not effective.
Test failures before launching the campaign
Use a small pilot with synthetic or authorised records. Test a sixth employee benefit, a proposed total above the current limit, a cash-redeemable voucher, a missing employment record, a public official without clearance, a duplicate recipient, an address entered by the wrong person, a non-EU parcel with no importer, a carrier timeout, a partial refund, and a deletion request. Each case should stop at the intended gate and name the person who can resolve it.
For the employee route, reconcile the ledger to payroll and the required Revenue report. For client gifts, reconcile approved recipients to invoices and actual dispatches. For imports, reconcile order value, commercial invoice, declaration, assessment, and payment. For privacy, trace a recipient from invitation through deletion and verify that exported copies and processor-held data follow the schedule.
Define acceptance evidence before the test. Screenshots alone are weak because they may omit time, actor, or underlying state. Prefer event logs, approval records, submission references, hashes, carrier receipts, correction histories, and deletion confirmations. Record the test data, expected result, observed result, owner, defect, fix, retest, and sign-off.
Monitor changes and revalidate material claims
This article’s official claims were last verified on 20 September 2026. Revenue guidance, reporting processes, VAT interpretation, customs rules, carrier restrictions, organisational gift policies, and privacy guidance can change. Record a source owner and review date for every material rule. Trigger early review when Revenue publishes an eBrief, the programme adds a new reward type, the legal employer changes, a new fulfilment region launches, or a processor changes its data locations.
Do not treat a copied threshold as configuration without provenance. Store the source URL, effective date, retrieved date, rule version, approver, and affected workflow. When a rule changes, identify open invitations and pending orders that relied on the old version. Decide whether they may proceed, need reapproval, or must be cancelled.
Maintain an information-gap register. The official full Act was verified, but its legal tests do not create a universal safe amount for public-official gifts, so no threshold was inferred. The general Revenue VAT pages do not provide one universal answer for every corporate gift, so finance review remains mandatory. These limits are reasons to keep decisions with qualified owners.
Measure control health with the percentage of sends that had complete approval before dispatch, unmatched employee-benefit events, reporting latency, duplicate prevention, customs exceptions, policy refusals, data retained past schedule, and time to close incidents. Avoid presenting delivery volume or redemption alone as compliance performance.
Make the final decision explainable and executable
An Irish corporate gifting programme is ready only when it can explain who the recipient was, why the item was appropriate, which owner decided each legal or financial question, what official rule and policy version applied, what data was used, how the parcel was declared, and what evidence closed the case. A product catalogue and a budget are not enough.
Start with recipient classification, preserve payroll ownership of the Small Benefit Exemption, keep client VAT and ethics analysis separate, require affirmative clearance for public-sector risk, collect addresses through a minimised recipient-controlled flow, and treat company parcels as commercial shipments. Build reporting, reconciliation, correction, and deletion into the launch plan rather than adding them after delivery.
Giftpack can serve as the execution layer after those decisions are made: it can present approved choices, collect recipient-controlled delivery details, and provide fulfilment events for reconciliation. It does not replace the employer’s payroll and tax conclusions, legal or ethics review, privacy governance, customs classification, or decision to send.